
Know your federal pension before you file.
Estimate your FERS pension in two minutes. Then sit down with Brandon Lloyd, CFP®, a fiduciary financial planner in Alexandria, to check the decisions you only get to make once: your retirement date, survivor benefit, health and life insurance, and your TSP.
Prefer a phone call? Request a call back
See what your pension could be
Use your best numbers. Your high-3 is your highest three consecutive years of basic pay, usually your last three, without overtime or bonuses. Your agency's retirement estimate and OPM's final figure are the official numbers.
An estimate using OPM's published formulas for full-time FERS service. It does not include part-time service, unpaid deposits or redeposits, military buyback, CSRS components or court orders. The supplement estimate uses Social Security's figure, which assumes you keep working to 62, so OPM's may be lower.
Six decisions you only get to make once
Your pension formula is set by law. These choices are not, and most of them are hard or impossible to change after you retire.
Retiring at your MRA with fewer than 30 years cuts your pension 5% for each year you are under 62, unless you postpone it. The month you leave also affects your annual leave payout and when your first payment starts.
A full survivor benefit costs 10% of your pension and pays your spouse 50% for life. A partial one costs 5% and pays 25%. Electing at least a partial benefit is also what lets your spouse keep FEHB if you die first.
To keep FEHB in retirement you generally need to be enrolled for the five years right before you retire. Then comes the Medicare Part B decision at 65, which is different for every household.
Coverage you keep in retirement can shrink or get much more expensive after 65 depending on what you elect. It is worth comparing with private coverage, or deciding you no longer need it, before you choose.
Installments, partial withdrawals, a TSP annuity, or a rollover: each has different taxes, flexibility and fees. If you separate in or after the year you turn 55 (50 for special provisions), you can withdraw without the early penalty.
The FERS supplement bridges you to 62 if you qualify. After your MRA it shrinks $1 for every $2 you earn above Social Security's limit ($25,560 in 2027). When to claim Social Security is a separate decision.
Your countdown checklist
- Ask HR for a retirement estimate and compare it with the estimator above. Big gaps usually mean missing service, a military deposit, or part-time periods.
- Check your eOPF. Make sure every SF-50 and any military or temporary service is there. Missing records are a common cause of delays.
- Confirm your FEHB and FEGLI five-year coverage so both carry into retirement.
- Decide the survivor benefit with your spouse. Spousal consent is required for anything less than the full benefit.
- Update your beneficiaries for FERS, FEGLI, TSP and unpaid compensation.
- Plan your annual leave payout. It is paid as a lump sum and taxed in the year you receive it, which matters for a December retirement.
- Build a cash cushion for the months between your last paycheck and OPM's final pension amount.
- Choose your TSP withdrawal plan before you need the money, not after.
Offered an early out? Run the numbers first.
Agencies are still reorganizing, and the rules differ by program. Check your eligibility on your separation date before you accept.
Sit down with a CFP® before you file
One meeting at our Alexandria office, right off I-395 at Duke Street. We go through your numbers together and you leave with a written summary.
- Your pension, supplement and survivor benefit, checked against your service history
- The best retirement month for you, including MRA+10 and early out options
- FEHB, Medicare and FEGLI choices for your household
- A TSP withdrawal plan and how it fits with Social Security and taxes
- No cost and no obligation. You decide what, if anything, to do next.
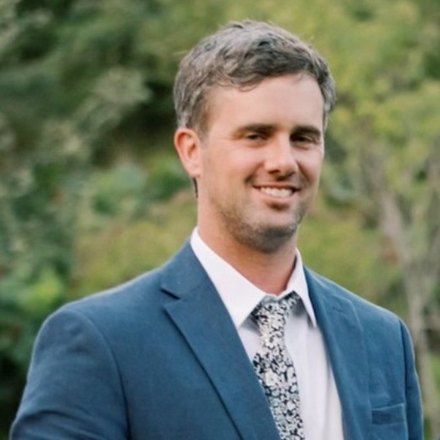
Brandon Lloyd, CFP®Founding Partner & President, Mountain View Wealth Management. A fiduciary, required to put your interests first. About Brandon
Request your review
About two minutes. We will call or text within one business day to set a time. Prefer to talk now? Call or text (571) 368-6178.
FERS retirement questions
How is a FERS pension calculated?
Most FERS employees receive 1% of their high-3 average salary for each year of creditable service. If you retire at 62 or older with at least 20 years, the factor is 1.1%. Law enforcement officers, firefighters and air traffic controllers receive 1.7% for each of their first 20 years and 1% after that. Unused sick leave is added to your service for the calculation, but it cannot be used to become eligible.
What is my minimum retirement age (MRA)?
It depends on your birth year: 55 if born before 1948, 56 if born 1953 through 1964, and 57 if born in 1970 or later. The years in between add two months per year. With 30 years of service you can retire at your MRA with no reduction.
When does the FERS supplement stop?
At 62. It is paid if you retire on an immediate, unreduced pension before 62 (MRA with 30 years, or 60 with 20), under special provisions, or under an early out once you reach your MRA. It is not paid under MRA+10. After your MRA it is reduced $1 for every $2 you earn above Social Security's annual limit, and it does not get cost-of-living adjustments.
Do FERS retirees get cost-of-living adjustments?
Regular FERS retirees generally start receiving COLAs at 62; special-provision and disability retirees receive them earlier. When inflation is above 3%, the FERS COLA is one point lower than Social Security's. For 2027 that is 2.6% for FERS and 3.6% for Social Security.
Should I elect the survivor benefit?
It depends on your spouse's own income, health coverage and your life insurance. A full benefit costs 10% of your pension and pays your spouse 50% for life; a partial benefit costs 5% and pays 25%. Electing at least a partial benefit is also what lets your spouse keep FEHB after you die. It is usually permanent, so model it before you file.
Should I keep my money in the TSP or roll it over?
The TSP's costs are very low, and for many people staying is the right answer. Others move some or all of it for more withdrawal flexibility, different investments, or to coordinate with other savings. We will show you the trade-offs in writing, including what it would cost to work with us, before you decide anything.
Is Mountain View affiliated with OPM?
No. Mountain View Wealth Management is an independent registered investment adviser and is not affiliated with or endorsed by the Office of Personnel Management or any government agency. Your official benefit amounts come from your agency and OPM.
Your pension is set by law. Your choices are not.
Get a second set of eyes on your federal retirement before you file, in person, at no cost.
Book a Complimentary Review Or call or text (571) 368-6178. 6001 Tower Ct., Alexandria, VA 22304.