Today's MYGA Rates · Virginia
Today's top guaranteed annuity rates in Virginia.
For each 3, 5 and 7-year term we show two multi-year guaranteed annuity (MYGA) rates: the highest rate we can offer today, and the highest from an insurer rated A- or better by AM Best. Checked every morning across more than 50 products, with the insurer, rating, surrender period and free withdrawals for each, so you can compare more than the number.
Prefer a phone call? Request a call back
3-Year GuaranteeHighest rateCall
for today's rate
- AM Best rating
-
- Surrender period
-
- Free withdrawals
-
Get This Rate Highest from A- or better insurersCall
for today's rate
- AM Best rating
-
- Surrender period
-
- Free withdrawals
-
Get This Rate
5-Year GuaranteeHighest rateCall
for today's rate
- AM Best rating
-
- Surrender period
-
- Free withdrawals
-
Get This Rate Highest from A- or better insurersCall
for today's rate
- AM Best rating
-
- Surrender period
-
- Free withdrawals
-
Get This Rate
7-Year GuaranteeHighest rateCall
for today's rate
- AM Best rating
-
- Surrender period
-
- Free withdrawals
-
Get This Rate Highest from A- or better insurersCall
for today's rate
- AM Best rating
-
- Surrender period
-
- Free withdrawals
-
Get This Rate
Two good choices, just different. Both insurers are rated by AM Best in its “Secure” range (B+ or higher), and both rates are guaranteed for the full term. The first pays the most today. The second comes from an insurer rated A- or better, the “Excellent” tier or above, usually for a slightly lower rate and often with a yearly free withdrawal. Which fits depends on what matters more to you: the highest rate or the higher rating.
Call or text (571) 368-6178 for today's rates.
For educational purposes only. Rates are shown for comparison and are not a recommendation or an offer to sell; suitability is reviewed before any application is submitted.
Speak with an advisor now
Questions about a rate, a term or moving money from a CD or another annuity? Call, text or email. You will reach a licensed agent, not a call center.
Ready to purchase?
Complete the application questionnaire (about 10 minutes). We review it, prepare your application and send it to you for e-signature.
Start the Questionnaire
Coming from a CD or savings account?
A MYGA works a lot like a CD: a fixed rate for a set number of years. It is not the same product, though. Here is how they compare.
| Feature | Bank CD | MYGA (fixed annuity) |
|---|
| What it is | A bank deposit for a set term | An insurance contract for a set term |
|---|
| Rate | Fixed for the term | Fixed for the term |
|---|
| Who backs it | FDIC insurance, up to $250,000 per depositor, per bank, per ownership category | The issuing insurer's claims-paying ability; not FDIC insured |
|---|
| Taxes on interest | Taxed each year, even if you leave it in | Tax-deferred until you withdraw it |
|---|
| Taking money out early | An early withdrawal penalty, often several months of interest | Some contracts allow a yearly free withdrawal; more than that during the surrender period carries a surrender charge and may have a market value adjustment |
|---|
| Before age 59½ | No IRS penalty | Taxable interest withdrawn may face a 10% federal tax penalty |
|---|
A MYGA can fit money you will not need for the full term. Keep your emergency fund in savings.
How it works
1Pick your rateChoose the term that fits how long you can leave the money untouched.
2Complete the questionnaireAbout 10 minutes: ownership, beneficiaries, and the financial details insurers require.
3We review and send your applicationWe review your answers, prepare the application and contact you to go over it before you e-sign.
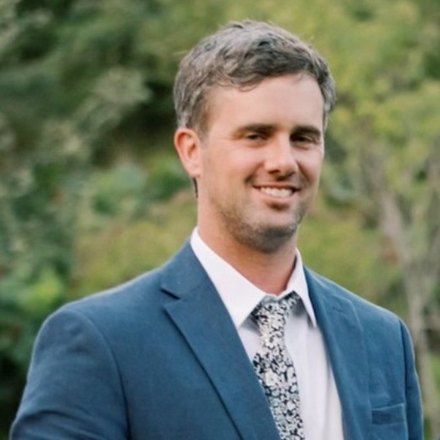
Who you'll work with
Brandon Lloyd, CFP®
Founding Partner & President, Mountain View Wealth Management · Licensed Virginia insurance agent
Brandon began his career in private equity in 2010 and went on to Wells Fargo Advisors before founding Mountain View Wealth Management in Alexandria. He is a CERTIFIED FINANCIAL PLANNER™ professional and holds a B.S. in Finance from James Madison University.
Every questionnaire is reviewed by a real person, and you go over the contract together before anything is signed.
More about Brandon →
Before you choose
Surrender chargesTaking out more than the free amount before the term ends costs a surrender charge, and some contracts add a market value adjustment. Choose a term you can wait out.
Free withdrawalsSome contracts allow a yearly withdrawal, such as 10% or the interest earned, without a charge. Others allow none. The cards show which.
Insurer strengthThe guarantee is only as strong as the insurer behind it. AM Best rates insurers from A++ down: A++ and A+ are Superior, A and A- are Excellent, B++ and B+ are Good. All of these are in AM Best's Secure range. We show each rating so you can weigh rate against strength.
At the end of the termWhen the guarantee period ends, you can usually renew at the insurer's new rate, move the money, or take it out without a surrender charge.
Want to go over the details together?If you'd like, we can schedule a time to walk through the specifics, like surrender charges, withdrawals, insurer strength and taxes, and how each could affect your decision. Complimentary, with no obligation.
Schedule a Time
Annuities are offered by Brandon Lloyd individually, as a licensed Virginia insurance agent. Annuity purchases are insurance transactions, separate from the advisory services of Mountain View Wealth Management, LLC, a registered investment adviser. He receives a commission from the insurer, which we explain before you buy. Rates shown are the highest available, and the highest available from an insurer rated A- or better by AM Best, through our quoting platform on the date shown, for a $100,000 single premium in Virginia; they change often, can differ by amount and age, and are subject to insurer approval. Once a contract is issued, its rate is guaranteed for the stated term. Multi-year guaranteed annuities are insurance contracts, not bank deposits; they are not FDIC insured, and guarantees depend on the claims-paying ability of the issuing insurer. Withdrawals above any free withdrawal amount during the surrender period are subject to surrender charges and may be subject to a market value adjustment. Withdrawals may be taxable and, before age 59½, may be subject to a 10% federal penalty. AM Best ratings are as shown on our quoting platform and can change. A listed rate is not a recommendation; your answers are reviewed for suitability before any application is submitted. © 2026 Mountain View Wealth Management LLC.
