
Your RMD can raise your Medicare premiums.
Required withdrawals add to your income, and Medicare looks at that income two years later. See this year's RMD, which Medicare surcharge tier it puts you in, how much room you have before the next one and where your income plan leaks. Then sit down with Brandon Lloyd, CFP®, to build one plan that coordinates all of it.
Prefer a phone call? Request a call back
Your RMD, your Medicare tier and where your income plan leaks
Use last year's tax return as a guide and your account balances from December 31 last year. Nothing you type leaves your browser unless you send it with a review request.
An estimate of federal income tax only, using the standard deduction, the extra deduction at 65 and the senior deduction for 2025 to 2028. It leaves out Virginia tax, itemized deductions and credits. Medicare tiers use the 2026 brackets, the latest published; the brackets that apply to this income will be set later and are usually higher. The survivor check assumes the survivor keeps the larger Social Security benefit (two-thirds of the household total) and the rest of the income.
One plan for every dollar you draw
Your RMD, Social Security, pensions, Medicare premiums, taxes and charitable giving all come out of the same income. Handle them one at a time and money leaks: a bracket here, a Medicare line there, a bigger tax bill for whichever of you outlives the other. An efficient income plan coordinates all of them, every year, so you get the income you need for the least total tax and Medicare cost over your whole retirement.
Handled one piece at a time
- The RMD comes out in December, from whichever account is handy
- Roth conversions are a guess, or never happen
- The Medicare surcharge arrives as a surprise letter
- The goal is this April's tax bill
- The survivor's taxes are left to chance
An efficient income plan
- Each account's withdrawal is set for the year, in the right order
- Conversions are sized to the dollar, under the next bracket and Medicare line
- Your Medicare tier is planned two years before the bill
- The goal is the least tax over your lifetime, and your heirs'
- Both of you, and the survivor, are planned for
How Mountain View builds your income plan
Every account, pre-tax, Roth and taxable, plus Social Security, pensions, annuities and what you actually spend.
Taxes, RMDs, Medicare tiers and Social Security taxation for each year into your 90s, for both of you and for the survivor.
How much to draw from each account, how much to convert to Roth, what to give from your IRA, and by when.
For clients, we revisit the plan before every December 31 with the new brackets, balances and laws.
This is the work we do for retirees in Alexandria, Arlington and Fairfax. Your first meeting is complimentary, and you leave with a written plan for this year and the next few.
Your income this year sets your Medicare bill in two years
Medicare charges higher earners an income-related monthly adjustment amount, or IRMAA, on top of the Part B and Part D premiums. Social Security sets it from the tax return you filed two years earlier.
Your RMD, pensions, part of your Social Security, interest, gains and any Roth conversion. Tax-free bond interest is added back for Medicare.
Your 2026 adjusted gross income plus tax-free interest becomes your modified adjusted gross income, or MAGI.
Social Security uses that 2026 MAGI to set your 2028 Part B and Part D premiums, per person, for the whole year.
Two things most people miss. First, the brackets are cliffs: one dollar over a line costs the full surcharge for that tier, for each person on Medicare. Second, when one spouse dies, the survivor usually files as single the following year with much of the same income, so the surcharge and tax lines drop to about half. Planning while you are both here, often with Roth conversions, can soften that.
What each Medicare tier costs
Official 2026 figures from the Centers for Medicare & Medicaid Services, based on 2024 income. Medicare adjusts the lines for inflation each year; the 2027 brackets are expected in mid-November.
| 2024 MAGI, single | 2024 MAGI, joint | Part B per month | Part D added | Extra per person, per year |
|---|---|---|---|---|
| $109,000 or less | $218,000 or less | $202.90 | $0 | $0 |
| $109,001 to $137,000 | $218,001 to $274,000 | $284.10 | $14.50 | $1,148 |
| $137,001 to $171,000 | $274,001 to $342,000 | $405.80 | $37.50 | $2,885 |
| $171,001 to $205,000 | $342,001 to $410,000 | $527.50 | $60.40 | $4,620 |
| $205,001 to $499,999 | $410,001 to $749,999 | $649.20 | $83.30 | $6,355 |
| $500,000 or more | $750,000 or more | $689.90 | $91.00 | $6,936 |
Part D amounts are added to whatever your drug plan charges. Married people who file separately and lived together face different, steeper lines.
Eight ways to lower your RMDs and your Medicare bill
From age 70½, a qualified charitable distribution sent straight from your IRA to a charity counts toward your RMD and never shows up in your income. Up to $111,000 per person in 2026. Donor-advised funds do not qualify.
The years between retirement and your first RMD are often your lowest-tax years. Moving some savings to a Roth then shrinks future RMDs, and Roth IRAs have none during your lifetime. Medicare looks back two years, so conversions done before the year you turn 63 never touch your premiums.
Size each year's conversion or gain to land just under the next tax bracket or Medicare line. A few thousand dollars over a line can cost more than the whole conversion saved.
Your first RMD can wait until April 1 of the next year, but then you take two in one year. For many people that pushes income over a Medicare line.
Tax-free bond interest, fund capital gain distributions, a home sale above the exclusion and a large one-time withdrawal all count. Timing them across years can keep you under a line.
If you retired, cut back, lost a pension or a spouse, married or divorced, Form SSA-44 asks Social Security to use your newer, lower income instead of the two-year-old return.
Your current employer's 401(k) can usually wait until you retire, unless you own more than 5% of the company. IRAs and old employers' plans cannot.
A surviving spouse files single with lower brackets and lower Medicare lines. Shifting money to Roth while both of you are here often lowers the survivor's taxes and premiums for years.
Your year-end checklist
- Add up every RMD. IRA RMDs can be taken from any one of your IRAs; 401(k) RMDs come from each plan; inherited IRAs follow their own rules.
- Take it by December 31. Only the first one can wait until April 1. Missing one costs a 25% excise tax, cut to 10% if you fix it within two years.
- Send charitable gifts directly from the IRA, early enough for the check to clear this year.
- Size any Roth conversion last, once you know this year's income, so it stops short of the next bracket or Medicare line.
- Have tax withheld from the RMD if you owe estimated tax. Withholding counts as if paid evenly through the year.
- Check your beneficiaries on every IRA and 401(k). They decide how quickly your heirs must empty the account.
- If your income dropped, file Form SSA-44 when your new premium notice arrives.
Sit down with a CFP® before December 31
One meeting at our Alexandria office, right off I-395 at Duke Street. We go through your numbers together and you leave with a written income plan for this year and the next few.
- One income plan: which accounts to draw from, how much, and in what order
- Your RMDs, checked across every account, and when to take them
- Your Medicare tier now and two years out, and how close you are to each line
- Whether Roth conversions make sense for you, and how much each year
- Charitable giving from your IRA, and an IRMAA appeal if your income dropped
- No cost and no obligation. You decide what, if anything, to do next.
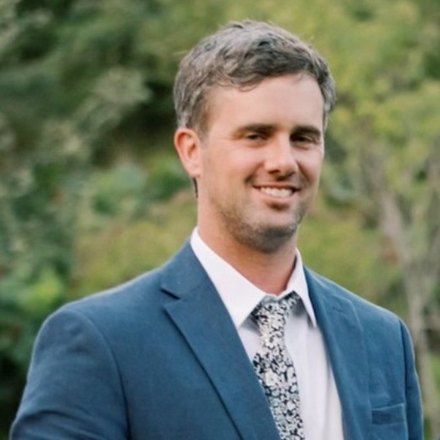
Brandon Lloyd, CFP®Founding Partner & President, Mountain View Wealth Management. A fiduciary, required to put your interests first. About Brandon
Request your review
About two minutes. We will call or text within one business day to set a time. Prefer to talk now? Call or text (571) 368-6178.
RMD and IRMAA questions
When do required minimum distributions start?
At 73 if you were born from 1951 through 1959, and at 75 if you were born in 1960 or later. Your first RMD is due by April 1 of the year after you reach that age; every later one is due by December 31. If you are still working, your current employer's plan can usually wait until you retire.
How is my RMD calculated?
Divide each account's balance on December 31 of the prior year by the factor for your age in the IRS Uniform Lifetime Table: 26.5 at 73, 24.6 at 75 and 20.2 at 80. If your spouse is more than 10 years younger and the only beneficiary, a different IRS table gives a smaller RMD.
What is IRMAA?
The income-related monthly adjustment amount is an extra charge on Medicare Part B and Part D premiums for people with higher incomes. In 2026 it starts above $109,000 of modified adjusted gross income for single filers and $218,000 for joint filers, based on the tax return from two years earlier. Each person on Medicare pays it.
What income counts toward IRMAA?
Your adjusted gross income plus tax-free interest. That includes RMDs and other IRA withdrawals, Roth conversions, pensions, the taxable part of Social Security, interest, dividends and capital gains. Charitable gifts sent straight from an IRA and qualified Roth withdrawals do not count.
Can I appeal an IRMAA surcharge?
Yes, if your income dropped because of a life-changing event: you stopped or cut back work, lost pension income or income-producing property, your spouse died, or you married, divorced or had a marriage annulled. File Form SSA-44 with Social Security, with proof. You can also ask for a new decision if the tax information Social Security used was wrong.
Can I do a Roth conversion once RMDs start?
Yes, but that year's RMD has to come out first, and the RMD itself cannot be converted. A conversion after 73 adds to the same income your RMD does, so sizing it around the tax brackets and Medicare lines matters even more.
What happens if I miss an RMD?
The IRS charges a 25% excise tax on the amount you should have taken, cut to 10% if you correct it within two years. Take the missed amount as soon as you notice and file Form 5329; the IRS can waive the tax for a reasonable error.
What is an efficient retirement income plan?
A year-by-year plan for which accounts you draw from, how much you convert to Roth and what you give from your IRA, set so you get the income you need with the least total tax and Medicare cost over your retirement, including for a surviving spouse. It is updated each year as brackets, balances and laws change.
Is Mountain View affiliated with Medicare or Social Security?
No. Mountain View Wealth Management is an independent registered investment adviser and is not affiliated with or endorsed by Medicare, the Social Security Administration, the IRS or any government agency.
RMDs are required. Overpaying on them is not.
Get one plan for your withdrawals, taxes and Medicare premiums, built with you in person. The first meeting is complimentary.
Book a Complimentary Review Or call or text (571) 368-6178. 6001 Tower Ct., Alexandria, VA 22304.